Could your business survive 30 days without trading?

Caption:
Regular review of business-interruption insurance ensures that cover keeps pace with changing risks, protects cash flow, and supports recovery after unforeseen disruptions
📷 SUPPLIED
If something stopped your business from trading for 30 days, would it still be standing?
As we approach the festive season, it is a natural moment to put this question to the test. While many business owners insure their buildings, vehicles, equipment and stock, fewer have tested what would happen if an unexpected event forced them to stop trading for an extended period.
The real test of resilience is not simply whether you can replace what is lost, but whether you can meet your financial obligations while you recover.
Why now?
The festive period changes business risk as staffing levels fall, premises stand partly vacant, security routines change and stock levels rise. It is also an opportunity to check whether risk management and insurance arrangements reflect the business you operate today.
A 30-day resilience test will help you understand if your business would survive a month of downtime or if there are gaps that need to be plugged. These 10 questions provide a good base:
- Do we know the minimum monthly cash required to meet fixed obligations?
- Have we identified the critical assets, systems, people and suppliers our operations depend on?
- Are our buildings, equipment and stock insured at current replacement values?
- Does our cover reflect seasonal peaks in stock or trading activity?
- Have we estimated a realistic recovery period, beyond simply repairing the damage?
- Can we restore critical data and systems from tested backups?
- Do we have alternative premises, suppliers or ways of operating?
- Are emergency responsibilities and contact details documented?
- Has our adviser been informed of material changes to the business?
- Do we understand our policy’s conditions, limits, exclusions and documentation requirements?
A “no” or “not sure” is not necessarily evidence of underinsurance. It is a signal to investigate an assumption before it becomes a problem.
Now is also the right time to test alarms, access controls and emergency equipment, confirm security providers have the correct escalation contacts, secure high-value stock and equipment, and test data backups.
From a business-continuity point of view, business should update stock and asset records, review policy conditions relating to temporary closures, and keep insurer and claims contact details accessible off-site.
The real cost of interrupted trading
Interrupted trading quickly becomes a financial problem as well as an operational one.
Damage to a single machine, supplier, system or site can trigger downtime, lost revenue and cash-flow pressure. Extreme weather, cyber incidents and social unrest can further complicate recovery.
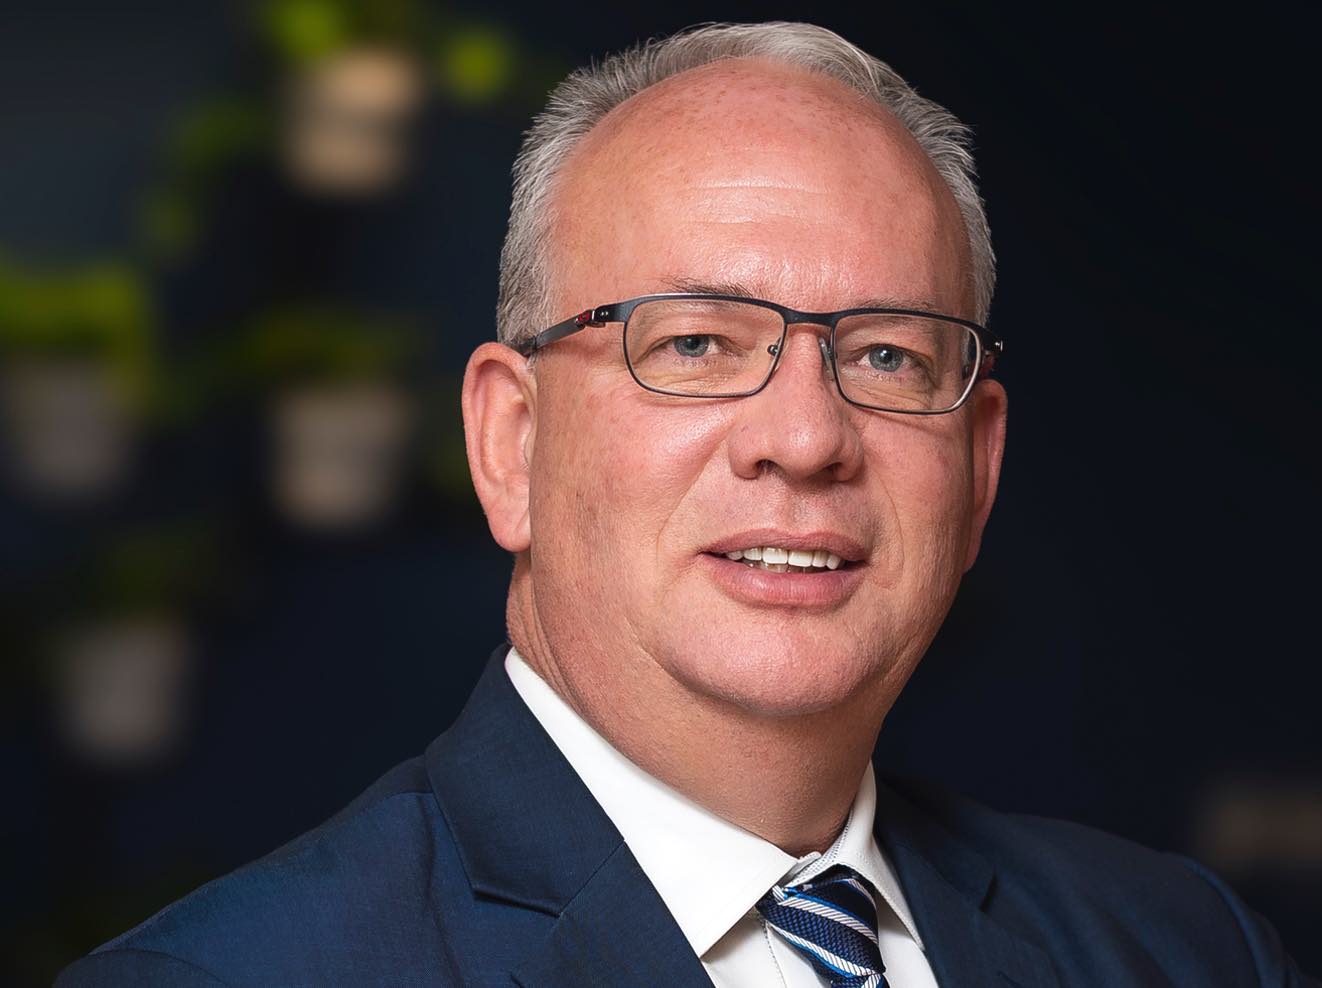
Caption: Johan van Greuning, CEO of Standard Insurance Limited
📷 SUPPLIEDWhile revenue slows or stops, salaries, rent, finance repayments, software subscriptions, security costs and supplier commitments may continue, and additional expenses such as temporary premises, replacement equipment and data recovery can arise.
Business-interruption insurance can help following an insured event, subject to the policy’s terms, limits, exclusions and indemnity period. But if cover is based on outdated turnover, gross-profit figures or unrealistic recovery assumptions, it may fall short of expectations.
The risk is not simply failing to insure your business. It is having cover that no longer reflects how your business operates.
Recovery time is not repair time
Repairing or replacing an asset is only one part of returning to normal trading. A realistic recovery estimate must account for loss assessments and approvals, equipment availability, imported components, temporary premises and the time needed to restore operations.
It should also consider reliance on single suppliers, critical skills or approvals, and how long customers will wait before taking their business elsewhere.
The most useful estimate is not the most optimistic one. It is the one supported by a practical recovery plan.
The pandemic demonstrated how disruption can affect businesses, suppliers, customers and infrastructure simultaneously. It also exposed the limitations of business-continuity plans that had never been tested.
How business growth creates an insurance gap
Underinsurance often develops gradually as a business expands but its insured cover remains unchanged.
Opening or relocating premises, buying machinery or technology, increasing stock, launching products or signing major contracts should prompt a review with your insurance adviser. So should significant increases in turnover or staffing, greater reliance on key suppliers, moving into online sales or collecting more customer data.
Insurance should evolve with the business, not simply roll over from one year to the next.
Making the most of your adviser
A good adviser can help by assessing how your business generates revenue, what could interrupt it, which costs would continue and what recovery would require.
When speaking to your adviser prepare updated asset and stock values, turnover and gross-profit figures, monthly revenue, payroll and fixed expenses. Include lease and finance commitments, details of critical machinery and systems, key supplier and customer dependencies, and existing continuity and backup arrangements.
Bring your current policy documents and highlight significant changes since your last review. This gives your adviser a basis for challenging assumptions and assessing the right combination of risk controls, continuity measures and insurance cover.
A risk partner for growing businesses
Standard Insurance Limited combines specialist commercial underwriting, risk advisory, tailored solutions, responsive service and specialist claims management.
Its capabilities include claims assessment, legal and recovery support, supply-chain management, actuarial expertise and data-led pricing.
Working with the broker market and the wider Standard Bank ecosystem, the business aims to understand clients’ operations, dependencies and growth ambitions. The objective is to help businesses protect the value they are building, rather than treating insurance as a standalone purchase.
Test your resilience before you need it
Before the year-end slowdown, work through the 30-day resilience test with your management team and an appropriately authorised adviser. Document your assumptions, identify gaps and agree on the actions that matter most.
If you do not yet have an adviser, or would like a second view, speak to your broker or contact the Standard Insurance Limited commercial team to arrange a commercial insurance review before your next renewal or expansion.
Remember, if your business cannot confidently explain how it would survive 30 days without trading, now is the time to find out, before an interruption does.
- Johan van Greuning is CEO of Standard Insurance Limited